Global TV and video trends shaping the connected TV era
This article is part of a series based on presentations from the HbbTV Symposium and Awards 2025, bringing together insights from across the industry on the future of broadcast services and connected television. Covering topics from broadband-only delivery and addressable advertising to interoperability and evolving standards, the series captures key discussions and expert perspectives shaping the next phase of HbbTV and the wider TV ecosystem.
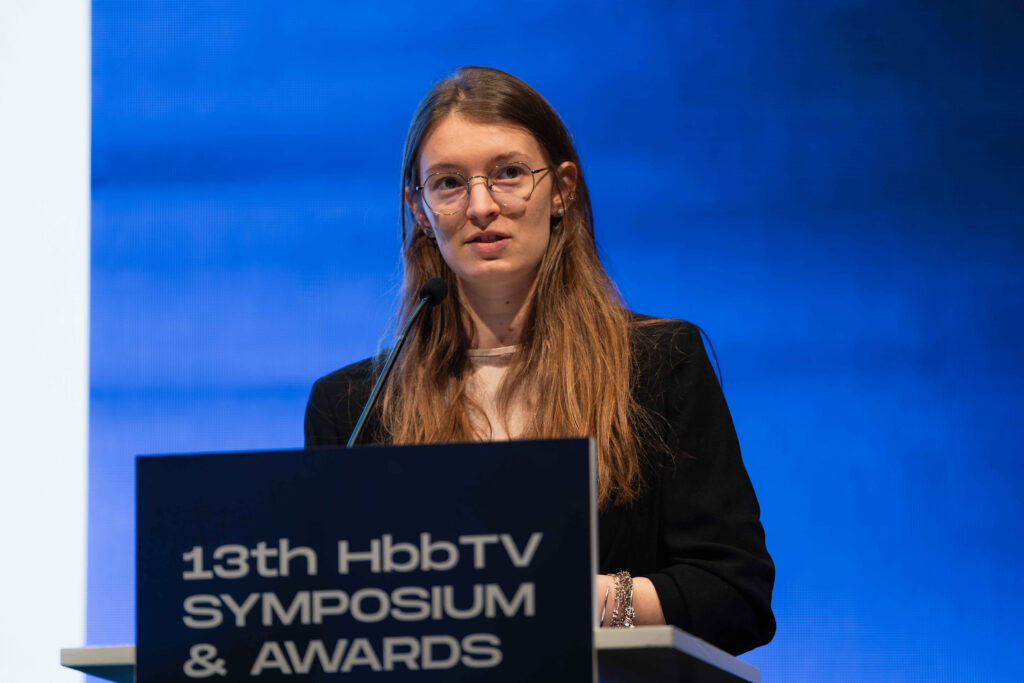
Ophélie Boucaud, Principal Analyst, Dataxis
At the HbbTV Symposium 2025, Ophélie Boucaud, Principal Analyst at Dataxis, presented a comprehensive overview of the global TV and video market, highlighting the scale, speed and complexity of the transformation underway.
Her analysis made one point immediately clear. Connected TV is now at the centre of the global television ecosystem. By the end of 2025, the number of active connected TV devices is expected to reach around 1.1 billion worldwide, reflecting the rapid adoption of internet-enabled viewing in living rooms across all regions.
Growth is not evenly distributed. Asia represents the largest market, driven by its scale and the high number of TV households, while North America and Western Europe show the highest levels of penetration, often with multiple connected devices per home. In contrast, regions such as the Middle East and Africa are still at an earlier stage of adoption, with lower levels of connectivity and device availability.
This expansion of connected TV is reshaping how audiences access content. Boucaud highlighted how these devices are enabling new forms of consumption, combining app-based viewing, interactivity and increasingly personalised user experiences. As a result, connected TV is set to overtake traditional pay TV platforms as the primary means of accessing television content within the next few years.
However, while the number of streaming households continues to grow, the market is beginning to mature. Paid streaming adoption is expected to plateau at around 40 percent of global households, driven by two parallel trends. Many users are subscribing to multiple services, while a growing segment of the audience is turning towards free, ad-supported alternatives.
Advertising is playing a central role in this evolution. The global connected TV advertising market is already valued at approximately 40 to 45 billion dollars and is expected to continue growing at a strong pace. This growth is being accelerated by the introduction of ad-supported tiers across major streaming platforms, which are now a significant component of subscription offerings in both North America and Europe.
At the same time, the competitive landscape is becoming increasingly complex. Fragmentation remains a defining characteristic of connected TV, both at the device level and within operating systems. Despite well identified market leaders (Samsung, LG, TCL…), no single manufacturer or platform dominates globally, and new entrants continue to emerge. This creates challenges for content providers, who must navigate a wide range of environments to reach audiences effectively.
The proliferation of applications further adds to this complexity. While app-based ecosystems provide flexibility and choice, they do not fully resolve fragmentation, particularly in areas such as billing and content discovery. As a result, visibility on device interfaces has become critical, with limited space available for content providers to reach viewers.
In this context, open standards such as HbbTV offer a valuable alternative. By enabling services to be deployed consistently across multiple devices and platforms, HbbTV provides broadcasters with a way to maintain reach and control in an increasingly fragmented environment. This solution has been praised by European broadcasters in some key markets, with BVOD services representing the vast majority of CTV apps natively on HbbTV.
Another major shift identified in the presentation is the ongoing migration of revenues towards digital platforms. Traditional television, including advertising, subscriptions and public funding, is expected to account for less than half of global industry revenues. In contrast, digital players, particularly video sharing platforms, continue to grow rapidly.
Companies such as YouTube, alongside major social media platforms, are capturing a significant share of advertising spend, driven by scale, targeting capabilities and strong audience engagement. This shift is particularly evident in mature markets such as North America and Europe, where traditional broadcasters are facing increasing pressure on revenues.
In response, broadcasters are adapting through a combination of digital transformation, partnerships and consolidation. New collaborations are emerging across content distribution, platform integration and advertising, reflecting a recognition that scale and cooperation are increasingly important in a competitive market.
Boucaud’s conclusion pointed to a rapidly evolving ecosystem shaped by three key forces:
- Connected TV is becoming the dominant device for home viewing.
- Online video is overtaking broadcast in both reach and monetisation.
- Advertising is shifting towards more targeted, performance-driven models.
For the industry, the challenge is to navigate this complexity while maintaining audience reach and engagement. As the presentation made clear, the future of television will be defined not by a single platform or model, but by the ability to operate effectively across an increasingly interconnected and dynamic landscape.
Watch the presentation and explore further
You can watch the full presentation from the HbbTV Symposium 2025 here: Watch the Video
The presentation slides are also available to download: Download the presentation
Next in the series
Dive into the fragmented world of smart TV operating systems, as Damien de Foucault explores the competing platforms, shifting strategies and evolving business models shaping how content is distributed and monetised across the connected TV ecosystem.